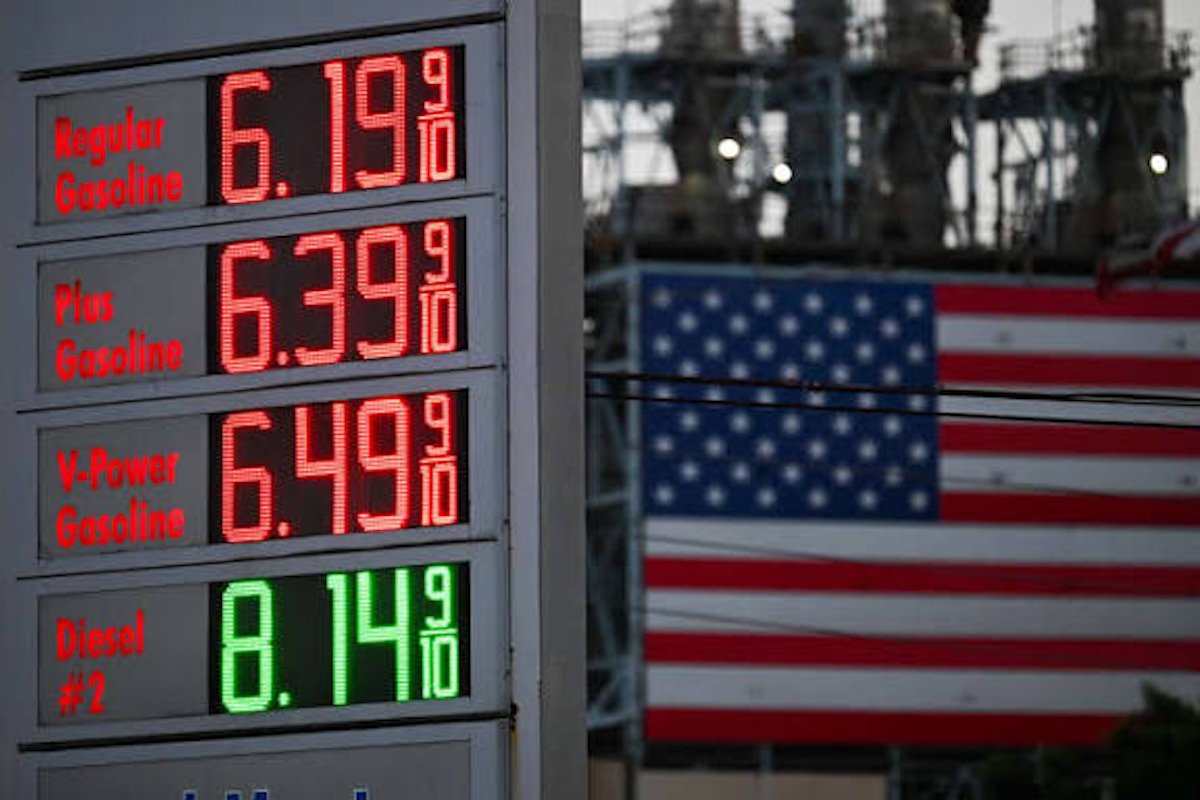
American diesel prices have climbed past $6.50 a gallon, a jump of roughly 75% from a year ago. That spike is not just a US problem—it is about to become Asia’s interest rate problem. Expensive diesel keeps US inflation elevated, giving the Federal Reserve reason to continue raising rates. Higher US rates lift the dollar and pull investment back toward America, leaving central banks across Asia to decide whether to tighten policy themselves to protect their currencies.
From US fuel pumps to Asian policy rooms
In the United States, the fuel squeeze has turned into a political crisis. Farm-state Republicans are pressing the White House to ban diesel exports before November’s midterm elections, and former President Donald Trump has said he is “very seriously considering” such a move. Several members of his own cabinet oppose the idea, as does the oil industry, and it is far from clear which way he will go. For Asian economies, his decision matters less than it might seem, because much of the inflation damage has already been done.
Diesel powers the trucks that stock supermarkets and the tractors that work American farms. A rise this steep gets passed on to shoppers over the following months, often well after the pump price has dropped out of the news. The Fed raised rates to between 3.75% and 4% in September, its first increase in three years. Most of its policymakers expect to move again before the end of 2026, and we agree with them.
Wednesday’s PCE figures, the Fed’s preferred inflation measure, came in softer than expected at 3.4% for the year to August, with core inflation at 3%. Some investors have taken this as a sign the Fed can relax, but we’d be wary of that reading. The figures were published alongside changes to how several parts of the index are calculated, so it’s hard to know how much of the improvement is genuine. Even taken at face value, 3.4% is well above the 2% the Fed is aiming for, and the diesel spike still hasn’t fully fed into prices.
An export ban wouldn’t solve much. It might ease prices in some parts of the US, though officials have been warned it could raise them in regions that rely on imported fuel. It would certainly hurt Europe, where diesel prices are at record highs and people have taken to the streets over them. The administration has also floated asking China to produce more diesel. None of this does much to calm a global fuel market under strain since the war involving Iran began seven months ago.
Asia’s currency and debt dilemma
Meanwhile, the dollar is close to its strongest level of the year, and US 10-year yields are above 5%. Both reflect expectations that the Fed has more work to do. Asia buys most of its oil and fuel from abroad and pays for nearly all of it in dollars. A stronger dollar makes those imports dearer in local terms even when global oil prices go nowhere. A trucking company in India or a fishing operator in the Philippines ends up paying more for fuel largely because of decisions made at the Fed.
Treasuries paying over 5% also draw in global investors, and some of the money that would otherwise go into Asian bonds and shares will head to the US instead. Those outflows weaken regional currencies further, which pushes import costs up again. Asian central banks have limited room to maneuver. Raising rates to support their currencies and contain imported inflation risks slowing economies already struggling with high energy costs, while holding back risks a sliding currency and fuel bills that climb even higher. We’d expect several of them to lean toward tightening over the coming months, particularly those whose currencies have already come under pressure this year.
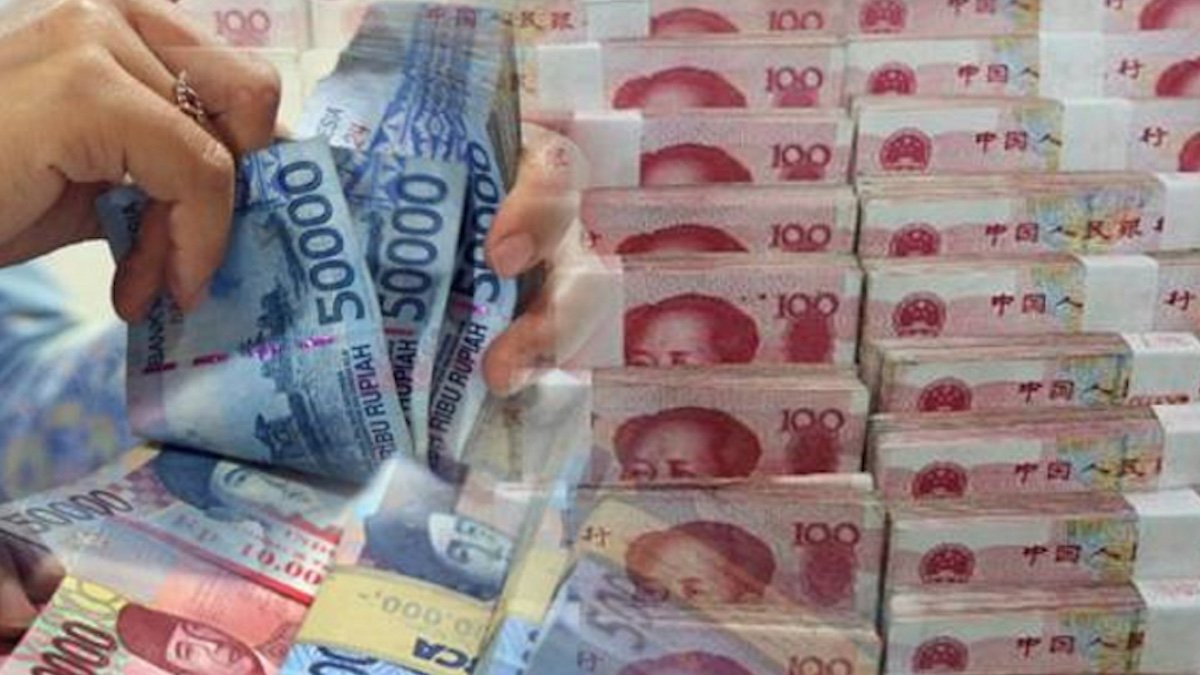
The impact won’t be spread evenly. Exporters with dollar revenues benefit from weaker local currencies, and Asian refiners could pick up extra business if American diesel stops flowing abroad. The economies most at risk are the big energy importers carrying a lot of dollar-denominated debt, and the Philippines tops that list. The peso hit a record low at the end of August and has lost almost 8% since the war with Iran began in February, largely because the country relies so heavily on imported oil. A strong dollar raises its fuel bill and makes foreign-currency debt more expensive to repay at the same time.
Indonesia is in a similar position. The rupiah sank to a record low in June, weaker even than at the depths of the 1997-98 Asian financial crisis. India, one of the world’s largest oil importers, has also seen the rupee fall to record lows this year. Investors with exposure to the region have good reason to look at how much of their portfolio sits in Asian currencies without a hedge. The same goes for holdings in companies that have borrowed in dollars while earning in local currency. Both could come under strain if the Fed keeps tightening into next year.
Trump may or may not ban diesel exports, and the midterm politics will play out either way. The inflation pressure behind the row has already reached the Fed, and from there it’s traveling toward Asia’s central banks. For a deeper look at how energy shocks are reshaping regional policy, see our analysis of Japan's energy security push and the broader challenges facing Indonesia's economy.