Two years ago, central bankers across the globe were close to declaring victory over inflation. Markets took that signal to heart, and many investors built portfolios on the assumption that the price surge of 2022 was a temporary blip. That assumption has now been proven wrong, and the consequences are visible across major economies simultaneously.
In the eurozone, prices are climbing at 3.8% annually, the fastest pace in three years. The US inflation rate has jumped to 3.7% after a 0.6% rise in September alone. Australia is running at 4%, and Britain at 3.1%, with petrol at its most expensive since late 2022. In India, inflation has risen for six consecutive months to reach 5.54%. These economies have vastly different growth rates, labor markets, and political pressures, yet they all face the same underlying problem.
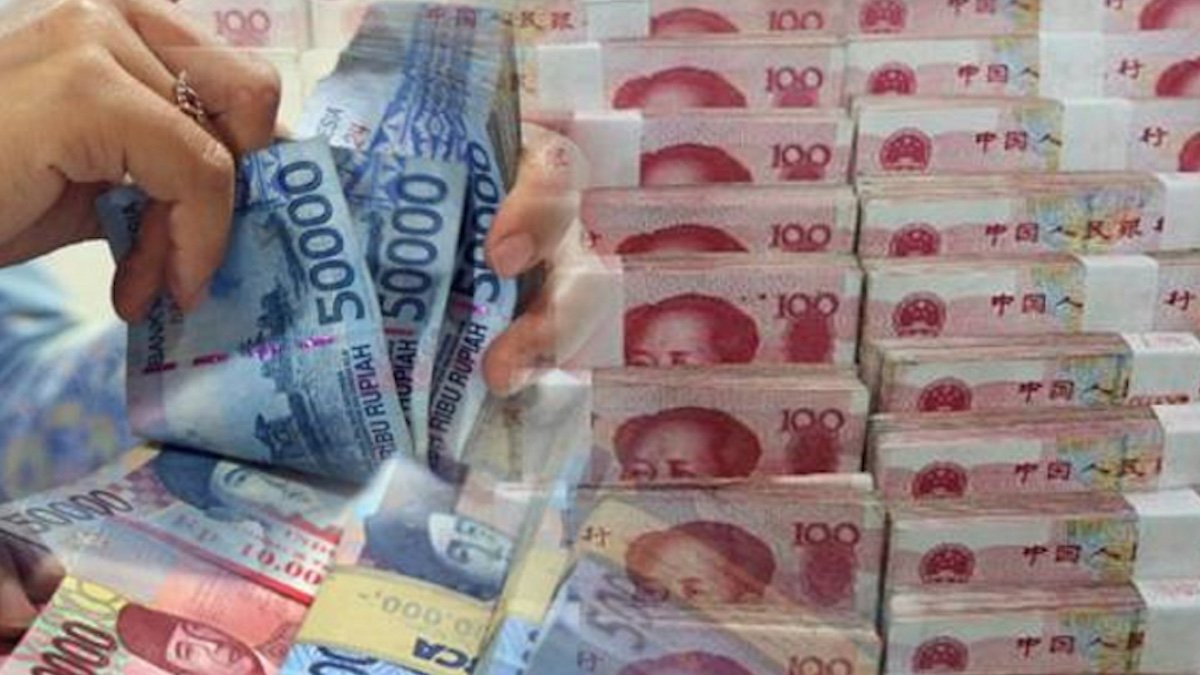
China, too, has shifted direction. For years, its factories supplied the world with cheap goods, helping to keep global prices low. Now, its factory prices are rising at their fastest pace since mid-2022, meaning one of the biggest deflationary forces has started to push prices up. This is a significant change with global implications.
Beyond the energy shock
It is tempting to blame the energy shock and assume inflation will fade once oil prices settle. The evidence suggests otherwise. US inflation has remained above the Federal Reserve's 2% target every month since March 2021, a stretch of more than five years. Core inflation, which excludes food and fuel, is also rising in the US, Australia, and India. In Europe, businesses are planning further price increases, and consumers expect to pay more in the coming year. Once such expectations take hold, they tend to become self-fulfilling: companies raise prices, and workers push for higher wages to keep up.
Central banks are responding. The European Central Bank has raised rates twice this year, the Federal Reserve has resumed hiking, and Australia, India, and Indonesia have all tightened. Further increases look likely. However, higher rates cannot produce more oil, and they take time to work. Policymakers are right to act, because letting today's price rises feed into wages would make the problem far harder to fix later. Even with their efforts, inflation looks likely to stay well above 2% for years.
What this means for investors
For investors, the effects hit across portfolios. Cash loses value fastest. At the current US inflation rate, money earning nothing loses half its purchasing power in under 20 years; at India's rate, it takes around 13 years. Savers who think they are being cautious fall behind every month their interest rate trails the cost of living. Bonds, long seen as the safe option, also come under pressure. A fixed return of 4% is worth very little when inflation runs close to that level, and each interest-rate rise reduces the market value of bonds already held.
The bigger risk is that shares and bonds fall together. Balanced portfolios rely on one cushioning the other. In 2022, the last time central banks raised rates this aggressively, both dropped sharply in the same year, and many investors who thought they were well diversified found far less protection than expected. Shares carry their own risks, with highly valued growth companies tending to suffer most when rates rise. Businesses that cannot pass higher costs on to customers see their profits squeezed, often just as those customers are cutting back to cover fuel, food, and mortgage bills.
Borrowers are hit twice: first by higher living costs, then by the rising cost of their debt. Wealth can still be protected, though it takes active management. Lower-risk, professionally managed strategies designed to keep pace with inflation at least leave investors far better placed than cash sitting idle. Real assets and businesses with genuine pricing power have historically held up best during long periods of rising prices.
A lasting shift
The way the consensus misjudged this deserves attention. Two years ago, the dominant view in central banks and on trading floors was that 2022 was a one-off, driven by lockdowns and supply bottlenecks that wouldn't return. Rates had done their job, prices were easing, and the world was heading back to the low inflation of the 2010s. However, much had changed beneath the surface. Energy markets remain fragile and highly exposed to geopolitical shocks. China is cutting excess factory capacity and no longer driving down the price of what it sells. Governments in the US, Europe, and much of Asia are running large deficits, adding demand just as central banks try to cool it.
Each of these pressures might be manageable on its own. Combined, they make a return to the low-inflation decade look increasingly unlikely. This changes how investors should judge success: a portfolio growing at 5% a year while prices rise at 4% has barely moved. The figure worth watching is real return, the growth in what wealth can actually buy, and it's a much tougher measure than the one most investors have relied on over the past decade.
Inflation rarely arrives with a single dramatic moment. Indeed, it works gradually, through grocery bills, energy costs, and mortgage statements, and through savings that look untouched on paper while buying less each year. It's now been back long enough, and across enough of the world, to be treated as a lasting part of the investment landscape. Policymakers will keep fighting it, and they may eventually win. Until then, the task for investors is to make sure their wealth grows faster than prices do. As bond markets signal persistent inflation fears, and with US diesel spikes pushing Asian central banks toward rate hikes, the pressure on the region is clear. Even Asia's central banks could turn bond vigilantes on Washington, adding another layer of complexity to the global inflation picture.