Southeast Asia's economic integration has long been a model of regional cooperation, and its retail payment systems now exemplify that success. Central banks across the bloc are linking national QR code protocols under the ASEAN Regional Payment Connectivity initiative, enabling seamless cross-border transactions for citizens of Indonesia, Thailand, Malaysia, and Singapore.
Yet as the speed and volume of cross-border capital flows surge, a critical vulnerability has emerged: criminal infrastructure moves at digital speed, while enforcement remains anchored to national borders. This mismatch is not merely a technical issue—it threatens the very foundation of the region's digital economy. As multi-currency payment rails become frictionless, they also lower the barriers for transnational financial crime.
Unless regulators act jointly now, rising cyber fraud could erode public trust—the bedrock of any financial market. If ordinary users come to see cross-border rails as unsafe, ASEAN's multi-billion-dollar integration push risks collapsing under its own structural flaws.
The connectivity paradox
Indonesia, the region's largest digital market, illustrates this contradiction. Bank Indonesia reports that QRIS transactions doubled year-on-year to 12.55 billion in the first half of 2026, crossing 600.7 trillion rupiah (US$38 billion). With 66 million users and 45 million merchants—mostly small neighborhood vendors—cashless payments are now woven into daily life.
However, rapid adoption has outpaced public understanding. Indonesia's National Financial Literacy and Inclusion Survey 2026 reveals a stark gap: financial inclusion stands at 93.61%, but financial literacy lags at 69.57%. This nearly 24-percentage-point gap creates a broad target for transnational cybercrime syndicates.
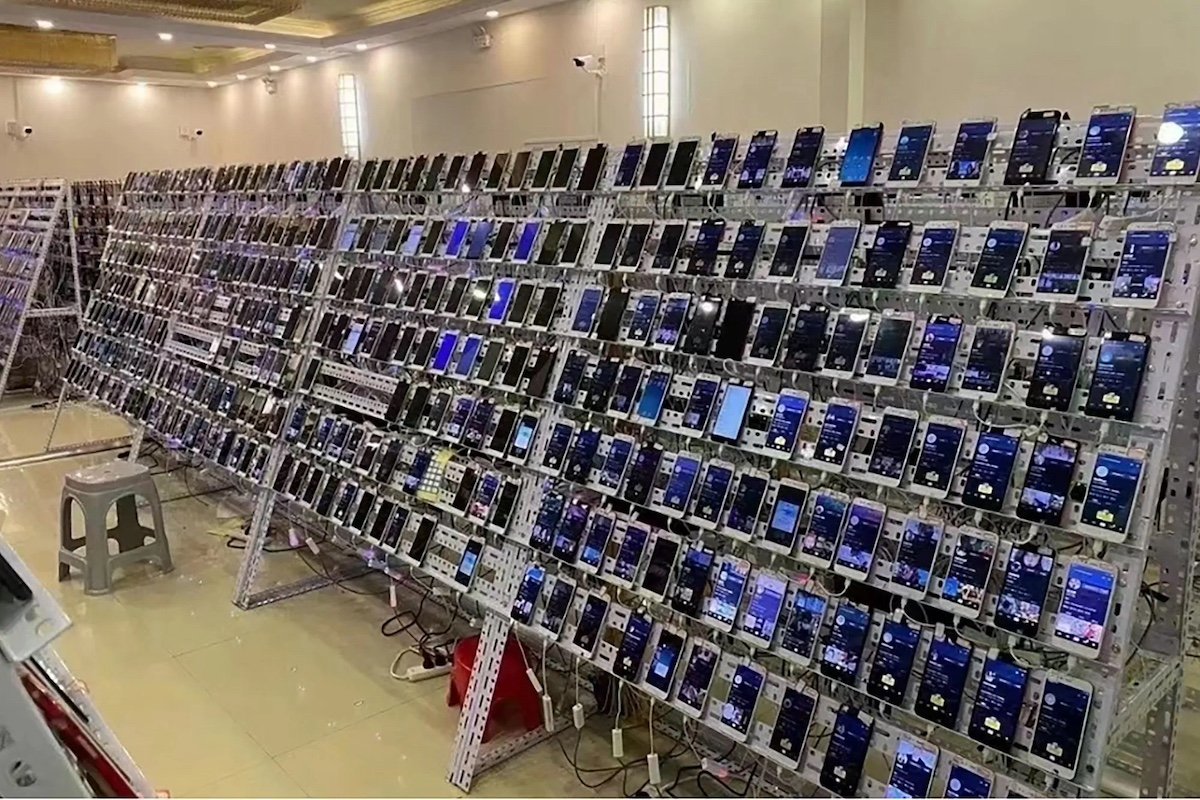
As highlighted in recent UNODC assessments on Southeast Asia's criminal economy, criminal groups exploit low digital literacy through social engineering, phishing, and elaborate mule-account networks, siphoning vast sums out of legitimate financial channels. This divide carries real human costs. Travelers making quick QR payments abroad often fall for fake codes or phishing traps, with little legal recourse when they return home. Migrant workers sending remittances to rural villages face targeted impersonation fraud, frequently watching life savings disappear with almost zero chance of cross-border recovery. Micro-merchants engaged in regional e-commerce suffer fraudulent account takeovers and unauthorized transaction reversals that threaten their cash flow and livelihoods.
Jurisdictional silos vs. real-time scams
The core challenge for regulators is a profound structural asymmetry. Today's financial scams move money across borders in milliseconds, while law enforcement remains trapped behind rigid borders, slow diplomatic channels, and mismatched national rules. By the time a victim reports a scam, the stolen capital has often been laundered across multiple borders and converted into unrecoverable digital assets.
This reality underscores a critical policy truth recently articulated by Bank Indonesia Deputy Governor Filianingsih Hendarta: “Technology can enable the growth of trust, but technology alone cannot create it. It is governance that creates it.”
Silicon Valley often pitches AI and blockchain as silver bullets for digital safety, but technology cuts both ways. Cyber syndicates build AI-driven phishing setups just as fast as banks build defense walls. Without clear cross-border rules, shiny digital rails simply scale up the threats instead of solving them.
Recognizing this, Bank Indonesia introduced Regulation No. 6/2026 on Consumer Protection, embedding risk-based oversight into its 2030 Payment System Blueprint. Central to this is the Indonesia Anti-Scam Centre (IASC), an integrated mechanism designed to accelerate real-time detection, reporting, and fund freezing in collaboration with domestic law enforcement and international bodies like Interpol, the OECD Financial Consumer Protection Task Force, and the Asian Development Bank (ADB).
Regional anti-scam architecture
While national initiatives like the IASC are a vital first step, a purely domestic defense is inadequate against an international threat. To safeguard its economic ambitions, ASEAN needs to upgrade these local efforts—including multilateral architectures like BIS Project Nexus—into a binding regional security pact.
First, central banks and Financial Intelligence Units across the bloc must link up for real-time data sharing. A suspicious transaction flagged in Jakarta or Bangkok should trigger an immediate, automated alert across neighboring banking networks, enabling the instant freezing of compromised accounts before capital can be funneled into offshore havens.
Second, the region must move toward a harmonized regulatory framework for cross-border emergency asset recovery. Waiting months for traditional diplomatic channels to freeze stolen assets renders consumer protection meaningless. ASEAN needs an expedited administrative protocol dedicated specifically to digital financial crime.
Finally, the private sector—including payment system operators, commercial banks, and big-tech platforms—must be held to higher standards of ethical responsibility. Platforms that profit from facilitating high-velocity transactions must be mandated to integrate real-time anomaly detection and built-in consumer protection mechanisms as a condition of operating across ASEAN's connected payment networks.
The stakes are high. As India and Indonesia's hidden role in Southeast Asia's scam industry shows, the region's criminal economy is sophisticated and deeply embedded. Without a coordinated regional response, the digital payment boom may become a double-edged sword—empowering economies while enabling crime. The time for action is now, before public trust erodes beyond repair.