For three decades, the semiconductor industry ran on a clear division of labor. TSMC printed chips. Memory makers like Samsung, SK hynix, and Micron packed capacitors. Designers like Nvidia, Apple, and Qualcomm drew the blueprints. And the money followed the drawing.
TSMC's neutrality was its greatest asset. It took designs from rivals and reproduced them in silicon without competing with its own customers. Companies trusted it with their most valuable intellectual property. Memory makers, meanwhile, were treated as manufacturers: fit more bits into less silicon, improve yields, lower cost per bit, and survive the next cycle. Pricing was brutal, and excess capacity could destroy profits overnight.
That order is now breaking apart. The next gains in chip manufacturing require the old partitions to dissolve. Design and manufacturing, logic and memory, packaging and die-printing—these boundaries are blurring. Power, heat, and data movement are making them harder to preserve. A company that can optimize across several of these layers now holds an advantage its competitors must answer.
This is the sequel to the story we told in Goliath's world, where giants began eating the hardware middle class. Now the giants are starting on each other. And the force driving this collision is Samsung's unusual shape—and its sudden ability to pay for it.
The shape advantage
Samsung is the only semiconductor company of its scale with a leading-edge memory business, a leading-edge logic foundry, and advanced packaging capabilities within the same corporate structure. In the three-dimensional manufacturing era the industry is entering, that shape is worth more than anyone has tried to put a number on.
For much of the past twenty years, that shape looked like a tax. The foundry consumed enormous capital while falling behind TSMC. Memory profits rose and fell with the cycle. Organizational silos meant that possessing several extraordinary capabilities did not automatically make Samsung extraordinary at combining them. Samsung itself was a prime example of a company spread too thin.
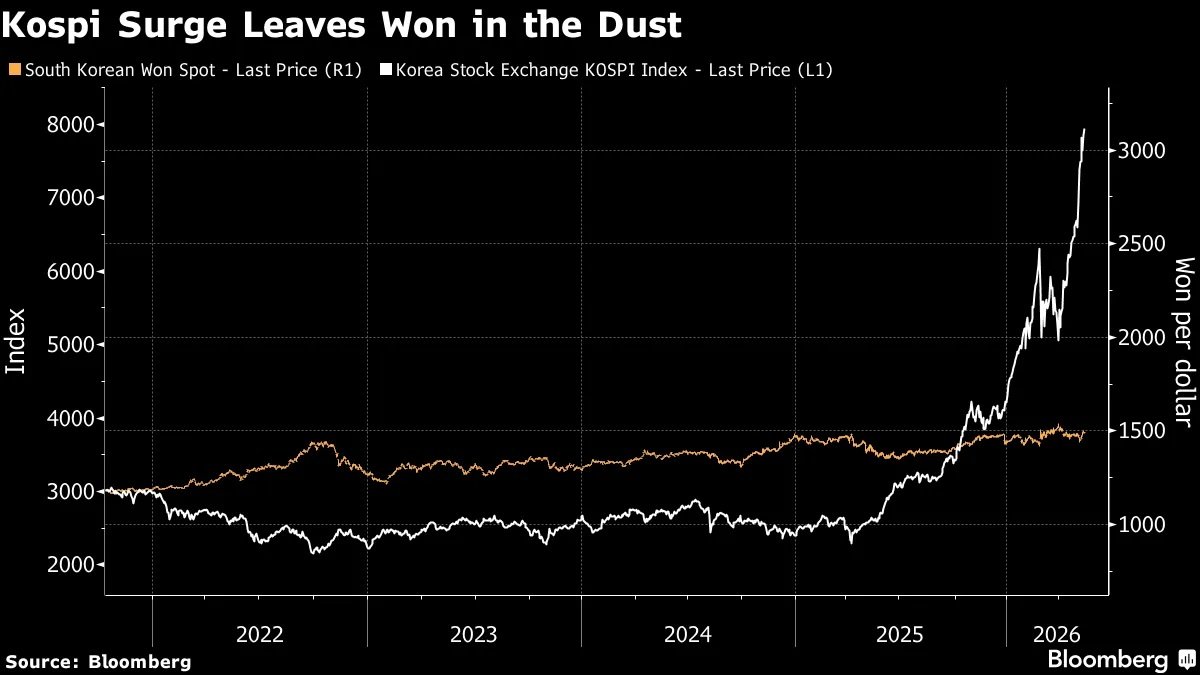
What changed is the money. Samsung's record profits—the largest in the history of human business—have given wings to its ambitions. It can now afford to push into the layer that used to tell it what to make. The foundries and memory makers, the two layers that spent decades taking what they were given, are now encroaching on the architects' territory.
Nvidia is extending its design authority into the memory stack itself. SK hynix and TSMC have been deepening an alliance neither needed while the old order held. Samsung, making both logic and memory, is the force they are arranging themselves against.
This mirrors what is already happening in software and services, where the monopolistic dominance of giants is eroding. The semiconductor industry is now experiencing its own version of that shift, and Samsung is at the center of it.
Two years ago, we wrote an open note to Warren Buffett suggesting he look at Samsung Electronics. The argument was never that Samsung was the best semiconductor company. TSMC is the better foundry, and SK hynix has taken the crown in high-bandwidth memory. Our case was about shape.
Samsung's shape—the combination of memory, logic, and packaging—is becoming a strategic asset. As the industry moves toward three-dimensional manufacturing, the control that shape makes possible is worth more than anyone has tried to quantify. The company that can optimize across these layers will hold an advantage that specialists cannot match.
The coming years will see intense competition among the semiconductor giants. Samsung's record profits have funded a push that could reshape the industry's power structure. The old division of labor is over. The giants are now colliding, and the outcome will determine who controls the next generation of chips.